
High Deductible Plan G vs Plan G
High Deductible Plan G vs Plan G comes down to how you balance monthly premiums and out-of-pocket costs.
Most people on Medicare have heard of Plan G. Fewer have heard of its cousin, High Deductible Plan G. For a lot of folks, it can save thousands of dollars a year on their Medicare supplement.
Let’s look at a real example. Meet Frank. Frank is 75 and lives in Denton County, Texas. Here is what Blue Cross Blue Shield charges him each month:
| Plan | Monthly premium | Yearly premium |
| Standard Plan G | $283 | $3,396 |
| High Deductible Plan G | $77 | $924 |
That is a difference of $206 a month, or $2,472 a year. So the big question is simple: is the high deductible plan worth it? Let’s break it down.
What Does Medicare Supplement Plan G Cover?
Original Medicare does not pay for everything. It leaves gaps, like the hospital deductible and the 20% you owe on most doctor bills. A Medicare supplement plan (also called a Medigap plan) fills in those gaps.
Medigap Plan G fills almost all of them. You pay one small thing: the Medicare Part B deductible, which is $283 in 2026. After that, Plan G pays the rest of your Medicare-approved costs for the year.
Think of it like a buffet. You pay a high price at the door, but then everything inside is covered.
How Does High Deductible Plan G Work?
High Deductible Plan G has the exact same benefits as standard Plan G. The only difference is when it starts paying.
You can also review Medicare.gov’s benefit chart when comparing High Deductible Plan G vs Plan G.
- You pay a yearly deductible first. In 2026, the High Deductible Plan G deductible is $2,950. Your $283 Part B deductible counts toward it.
- Medicare still pays its share. While you work toward the deductible, Medicare keeps paying about 80% of your doctor bills. You only pay the part Plan G would normally cover, like the 20%.
- Then the plan pays 100%. Once you hit $2,950, High Deductible Plan G covers your Medicare approved costs for the rest of the year, just like standard Plan G.
Here is an easy way to picture it. Imagine two phone repair plans. With one plan, you pay a lot every month and never pay for repairs. With the other, you pay very little each month, and you only pay for repairs up to a set limit. After that, every repair is free.
The key point: $2,950 is the most you would pay for Medicare approved care in a year. It is not a surprise bill that keeps growing.
One heads up: the deductible goes up a little each year. For 2027, it rises to $3,050.
High Deductible Plan G vs Plan G: Cost Comparison
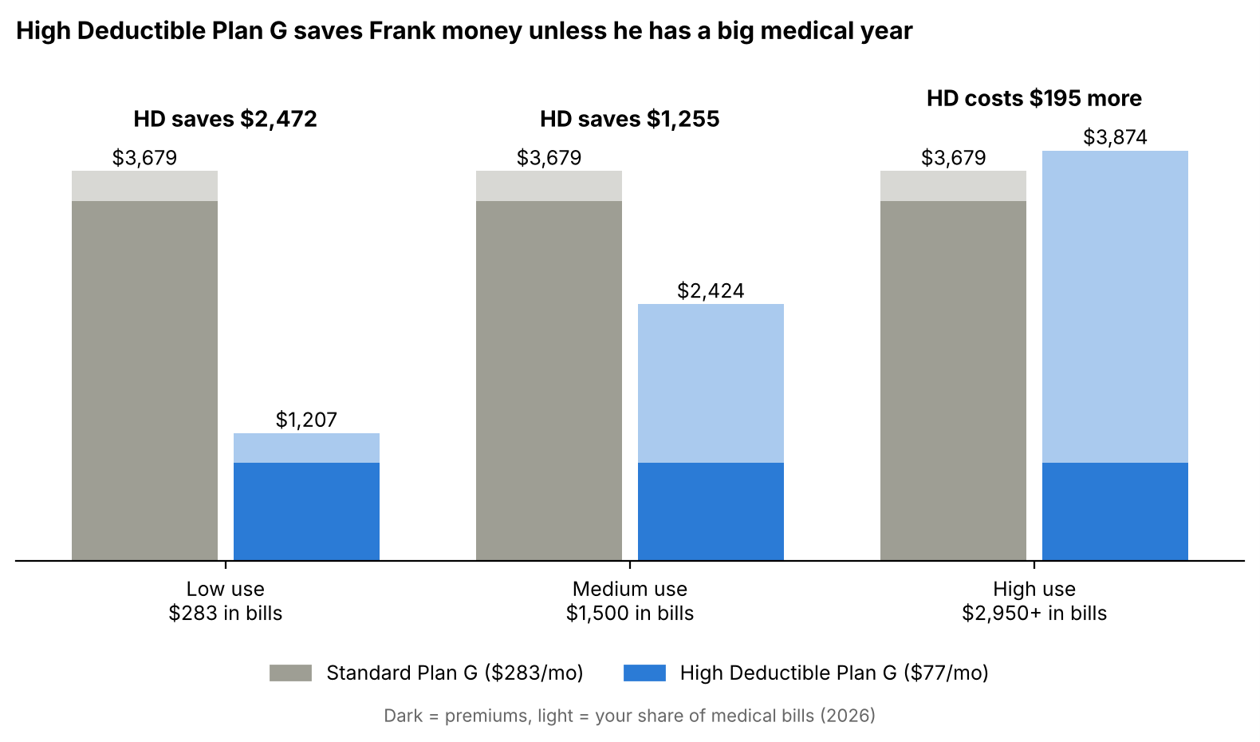
The real test is what Frank pays in a whole year: his premiums plus his share of medical bills. Here is how it plays out in three kinds of years.
Premiums: BCBS rates, 75 year old male, Denton County, TX. Deductibles: CMS 2026.
- Low use: a checkup and a few doctor visits. Frank only pays the $283 Part B deductible on either plan.
- Medium use: some tests, a scan or a few specialist visits. Frank pays more out of pocket, but the low premium still puts him way ahead.
- High use: a hospital stay or surgery. Frank hits the full $2,950 deductible, then the plan pays 100%.
Notice the worst case. In a really bad year, High Deductible Plan G costs Frank only about $195 more. In a good year, he saves almost $2,500.
Is High Deductible Plan G Right for You?
For Frank, High Deductible Plan G wins unless the part of his bills Medicare does not pay goes over $2,755 in a year. Even in a bad year, it only costs him $195 more than standard Plan G.
High Deductible Plan G may be a good fit if you:
- Are fairly healthy and see the doctor a few times a year
- Want the lowest Medicare supplement premium
- Have some savings set aside to cover the $2,950 deductible if you need it
- Want to see any doctor in the country who takes Medicare, with no networks
Standard Plan G may be better if you:
- Have ongoing health issues or expect surgery
- Want to know your exact cost every single year
- Would have a hard time paying $2,950 at once
One more tip: switching from High Deductible Plan G to standard Plan G later is not always easy. In Texas, you may need to answer health questions to change plans. So pick the one that fits you for the long run.
Get Help Comparing Medicare Supplement Plans in Denton County
High Deductible Plan G is not for everyone, but for many healthy seniors it is one of the smartest ways to save on a Medicare supplement. Frank could keep about $2,472 a year in his pocket and still have strong coverage if something big happens.
Rates change by age, zip code and insurance company. At Insurance Connection USA, we compare Medicare supplement plans in Corinth, Denton County and across Texas for free. Call us and we will run your numbers side by side.
If you have questions, contact us at 940-382-4700 or email Cassondra@icusa-tx.com. We can help you compare High Deductible Plan G vs Plan G using your own numbers.


